Moving from a Toronto condo to a Toronto townhouse costs more than the price gap suggests. Using September 2026 benchmarks, the gap is about $171,000, but selling costs, double land transfer tax and moving push the one-time cost of the switch to roughly $50,000 on top of that. In our worked example, the monthly mortgage payment rises by about $1,170 before you account for condo fees you stop paying and repairs you start paying for.
Key takeaways
- In the City of Toronto, the townhouse benchmark ($714,700) is $170,900 above the condo apartment benchmark ($543,800).
- Repeat buyers in Toronto pay both Ontario and municipal land transfer tax with no first-time rebate: $21,550 on a $715,000 townhouse.
- In our example, commission alone on a $545,000 condo sale is about $24,600, so budget selling costs before you shop.
- Moving up to a townhouse in Brampton or Milton costs far less than staying in Toronto; in Oshawa, the townhouse benchmark is below Toronto’s condo benchmark.
- Line up the sale and purchase dates, or ask your lender about bridge financing, before you firm up either deal.
How much more does a townhouse cost than a condo in Toronto?
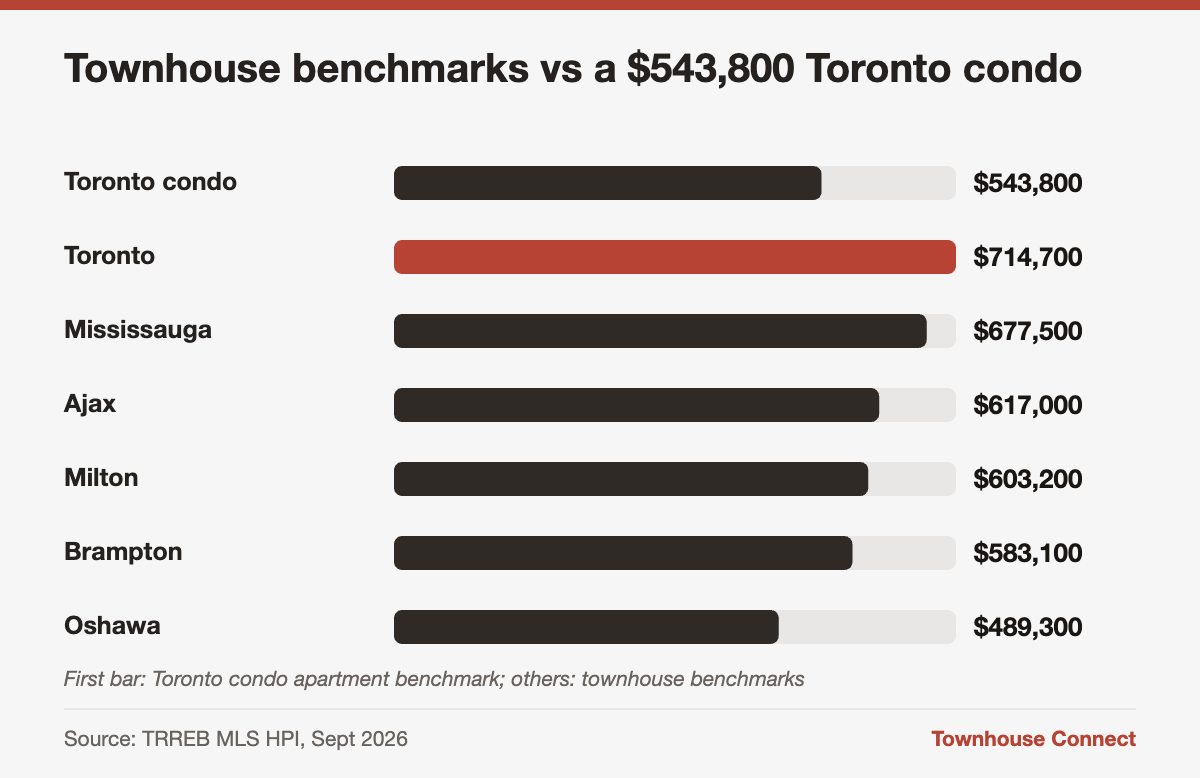
According to TRREB’s September 2026 MLS HPI tables, the City of Toronto benchmark was $543,800 for a condo apartment and $714,700 for a townhouse. Both are down from a year ago, by 6.36% and 5.04% respectively.
So the step up is about $170,900 on paper. Because both have fallen, your condo equity may be lower than it was a year ago. The good news is that a softer townhouse market gives you room to negotiate on the purchase side, with condo townhouses selling at an average of 98% of list price across the GTA in September.
A worked example: selling a $545,000 condo, buying a $715,000 townhouse
Here is a realistic illustration. The assumptions are labelled so you can swap in your own numbers.
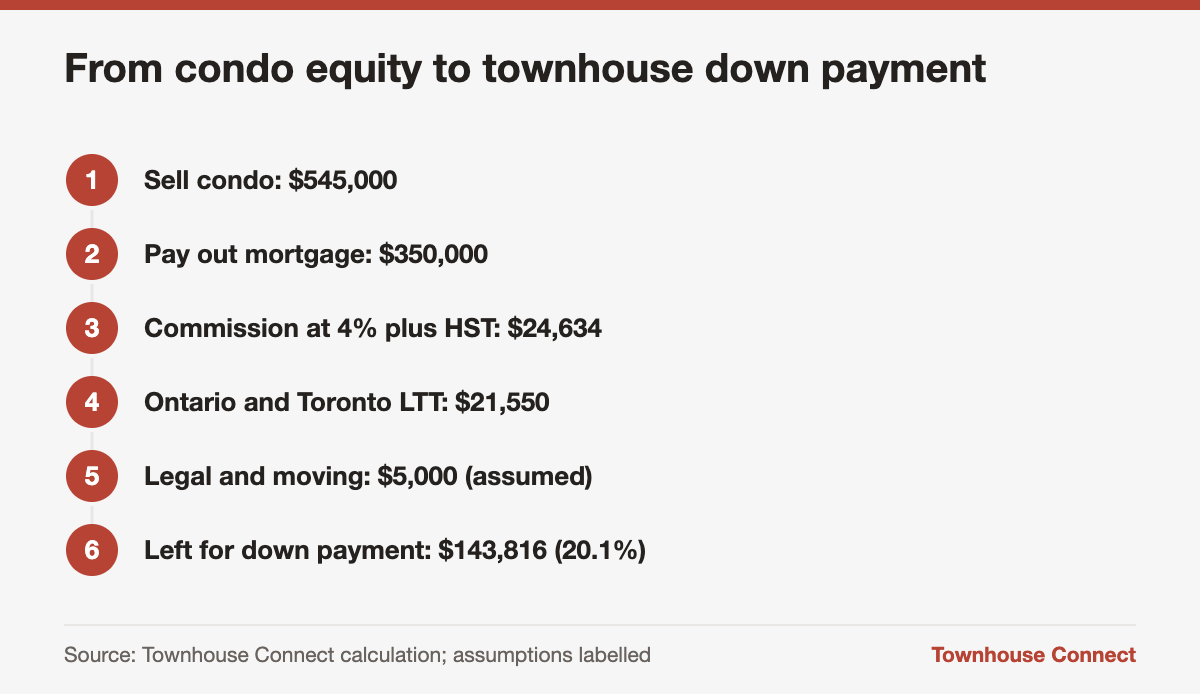
- Condo sale price: $545,000
- Remaining condo mortgage: $350,000 (assumption)
- Selling commission: 4% plus HST, for illustration only; commissions are negotiable
- Legal fees and moving: $5,000 combined (assumption)
- Townhouse purchase price: $715,000, in the City of Toronto
| Item | Amount |
|---|---|
| Condo sale price | $545,000 |
| Less mortgage payout | −$350,000 |
| Less commission (4% + HST) | −$24,634 |
| Equity after selling costs | $170,366 |
| Less Ontario land transfer tax on $715,000 | −$10,775 |
| Less Toronto municipal land transfer tax | −$10,775 |
| Less legal and moving (assumption) | −$5,000 |
| Available for the down payment | $143,816 (20.1%) |
That clears the 20% mark on a $715,000 townhouse ($143,000), so there is no CMHC premium. The new mortgage is about $571,200.
What happens to the monthly payment
At 5.09%, a typical mid-October uninsured five-year fixed rate, a $571,200 mortgage over 25 years costs about $3,351 a month. If your current condo mortgage is $350,000 with 20 years left at 4.34%, you are paying about $2,177 today. The difference is roughly $1,174 a month.
The payment is not the whole story, though.
- Fees you stop paying: if the townhouse is freehold, your condo fee disappears. Swap your own fee into the math.
- Fees you may start paying: a condo or POTL townhouse has its own fee, usually covering different things.
- Costs you take on: a freehold owner pays for the roof, windows, furnace and snow shovel, so set aside a repair budget each month.
- Property tax: it is based on MPAC’s assessed value, which still uses January 1, 2016 values, so it will rise with the more valuable home.
Land transfer tax: the cost move-up buyers forget
First-time buyers get up to $4,000 back from Ontario and up to $4,475 back from Toronto. You only get those once. If you or your spouse have owned a home before, including the condo you are selling, you pay the full amount.
On a $715,000 townhouse, that is $10,775 under the Ontario land transfer tax rates plus another $10,775 under the Toronto municipal rates. Move outside Toronto and the second tax disappears. That alone is a reason many condo owners in the city look at the 905 for their first townhouse.
Does moving to the 905 make the upgrade affordable?
Often, yes. The table compares the Toronto condo benchmark with townhouse benchmarks in nearby municipalities.
| Townhouse location | Townhouse benchmark (Sept 2026) | Gap vs Toronto condo ($543,800) | Ontario LTT only |
|---|---|---|---|
| City of Toronto | $714,700 | +$170,900 | $10,769 (plus Toronto MLTT) |
| Mississauga | $677,500 | +$133,700 | $10,025 |
| Ajax | $617,000 | +$73,200 | $8,815 |
| Milton | $603,200 | +$59,400 | $8,539 |
| Brampton | $583,100 | +$39,300 | $8,137 |
| Oshawa | $489,300 | −$54,500 | $6,261 |
The trade is commute and neighbourhood for space. If your work is hybrid, a Brampton townhouse at the benchmark costs only about $39,000 more than a Toronto condo, and you avoid the municipal tax. Our townhouse vs semi price comparison has more city-by-city data.
Sell first or buy first?
Both approaches work. Each has a risk.
Selling first
You know exactly how much equity you have, and you can shop with a firm budget. The risk is needing somewhere to live if you do not find a townhouse before your condo closes. A long closing date on your sale helps.
Buying first
You secure the townhouse you want, but you are carrying two properties if the condo takes longer to sell. With GTA inventory at about 4.6 months in September, that risk is real. If you buy first, price the condo to sell promptly and ask your lender whether bridge financing is available once you have a firm sale.
Tip: Before listing, ask your lender for the exact penalty to break your condo mortgage, and whether you can port it to the townhouse. Porting can avoid a penalty and keep part of your current rate, with new money blended in at today’s rates. The answer can change which closing dates make sense.
A move-up checklist
- Get a written estimate of your condo’s value and a sense of how fast similar units are selling.
- Get your mortgage payout statement and penalty figure.
- Get pre-approved for the townhouse mortgage, including any new money if you port.
- Decide on freehold, POTL or condo townhouse, and set a fee limit.
- Budget both land transfer taxes if you stay in Toronto.
- Coordinate closing dates with both lawyers, leaving a cushion of a few days if you can.
Our down payment guide for a $700,000 townhouse covers the insured route if your equity falls short of 20%.
Frequently asked questions
Is it worth upgrading from a condo to a townhouse in 2026?
It depends on your space needs and budget. Townhouse prices across the GTA are down 6.52% from a year ago, and condo townhouses are selling below list, which helps buyers. But condo prices are also down, so your equity may be lower than you hoped. Run the full numbers, including selling costs and both land transfer taxes, before deciding.
Do I get the first-time buyer land transfer tax rebate when upgrading?
No. The Ontario refund of up to $4,000 and the Toronto rebate of up to $4,475 are only for buyers who have never owned a home anywhere, and a spouse’s ownership also counts. If you are selling a condo you owned and lived in, you pay the full land transfer tax on the townhouse.
How much do I need to earn to move from a condo to a townhouse?
That depends on the new mortgage, property tax, heating and any condo fee. In our example, a $571,200 mortgage at 5.09% would qualify at the 7.09% stress-test rate, a payment of about $4,030 a month before taxes and heat. Lenders limit housing costs to 39% of gross income, so ask for a pre-approval with your figures.
Planning a move up? Browse Toronto townhouses, or talk to our team about timing the sale of your condo and the purchase together.
This article is general information as of October 2026, not legal, tax, mortgage or financial advice. Rules and numbers change, so confirm the details for your situation with a licensed professional.